Commercial Auto Coverage Guide
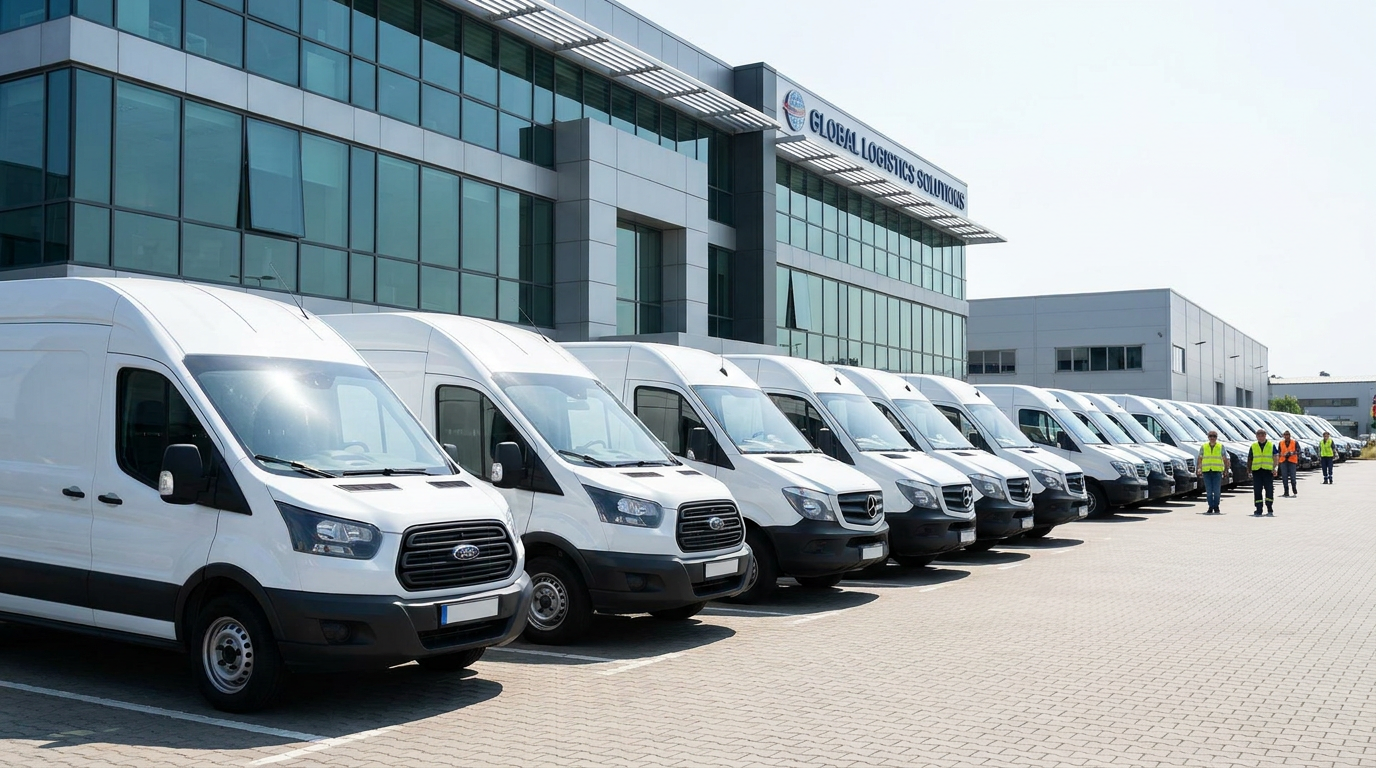
Why Commercial Auto Insurance Differs from Personal
If your business owns, leases, or regularly uses vehicles for work purposes, personal auto insurance is not enough. Commercial auto insurance is specifically designed for the unique risks that come with business vehicle use — higher mileage, multiple drivers, heavier cargo, and greater liability exposure.
At Vantage Insurance, our commercial auto specialists help businesses of all sizes build coverage that protects their vehicles, their drivers, and their bottom line.
Who Needs Commercial Auto Insurance?
Commercial auto insurance is essential for any business that:
- Owns cars, trucks, vans, or specialty vehicles used for business
- Has employees who drive company-owned vehicles
- Delivers products or transports goods
- Sends employees to job sites, client meetings, or service calls
- Uses vehicles for hauling equipment or materials
Even if your business only uses personal vehicles for occasional work errands, you may need a hired and non-owned auto policy to cover liability gaps that personal insurance does not address.
Coverage Components
A comprehensive commercial auto policy includes several coverage types:
Liability Coverage
This is the foundation of any commercial auto policy. It covers bodily injury and property damage your driver causes to others in an accident. Most states require minimum liability limits, but businesses should carry higher limits to protect against significant claims.
Collision Coverage
Pays to repair or replace your business vehicle after an accident, regardless of who is at fault. This is especially important for newer vehicles or those critical to daily operations.
Comprehensive Coverage
Covers non-collision events including theft, vandalism, fire, hail, animal strikes, and falling objects. For businesses that park vehicles outdoors overnight, comprehensive coverage is particularly valuable.
Uninsured/Underinsured Motorist
Protects your business when an at-fault driver has insufficient or no insurance to cover damages. Given the number of uninsured drivers on the road, this coverage is strongly recommended.
Medical Payments
Covers medical expenses for the driver and passengers of your business vehicle, regardless of fault. This provides immediate coverage while liability claims are being resolved.
Fleet discount: Businesses insuring multiple vehicles on a single commercial auto policy typically qualify for significant fleet discounts. Ask your Vantage agent about multi-vehicle pricing.
Hired and Non-Owned Auto Insurance
This often-overlooked coverage is critical for businesses whose employees use personal vehicles for work or who rent vehicles for business purposes. It covers:
- Liability when an employee drives their personal car on company business
- Liability for rental vehicles used for business trips
- Gaps between the employee's personal policy and the business's exposure
Factors That Affect Your Premium
Commercial auto insurance premiums are based on:
- Number and type of vehicles: Larger fleets and heavier vehicles cost more to insure
- Driver records: Clean driving histories across your team lower your rate
- Industry classification: Delivery services and construction companies face higher premiums than office-based businesses
- Radius of operation: Local operations cost less than long-haul or interstate routes
- Cargo value: Businesses transporting high-value goods need additional coverage
- Annual mileage: Higher mileage increases exposure and premiums
Risk Management Tips
Proactive fleet management can significantly reduce your commercial auto costs:
- Screen drivers carefully: Run MVR checks on all employees who will drive company vehicles
- Implement a vehicle maintenance program: Regular inspections prevent mechanical failures that lead to accidents
- Use telematics: GPS tracking and driver behavior monitoring identify risky habits before they cause claims
- Establish a written driving policy: Clear rules about distracted driving, speed limits, and personal use reduce risk
- Provide driver safety training: Annual defensive driving courses lower incident rates and may earn premium discounts
Get a Commercial Auto Quote
Whether you operate a single service van or a fleet of delivery trucks, Vantage Insurance has the commercial auto expertise to keep your business moving safely. Get your personalized quote in under five minutes.